
Measuring the ROI of Flexible Manufacturing Before Approving Automation Investment
A capital request for a new corrugator module, digital workflow, automated die-cutter, folder gluer, CNC nesting cell, or edge-banding line often arrives with an attractive headline: higher output, fewer operators, faster changeovers. Those claims may be directionally true, but they are not yet a finance-grade investment case. The approval question is whether the equipment will create incremental, collectible cash flow after its full cost, operational constraints, and ramp-up risk are accounted for.
The most reliable way to measure the ROI of flexible manufacturing is to treat flexibility as a set of measurable operating capabilities rather than a vague strategic benefit. A machine’s ability to run more SKUs, accept shorter lots, change jobs with less downtime, reduce setup scrap, and process customized orders has value only when it either lowers controllable cost, protects existing margin, or enables profitable demand that the current operation cannot serve. The investment model should make each of those links visible.
Start with the decision that is actually being funded
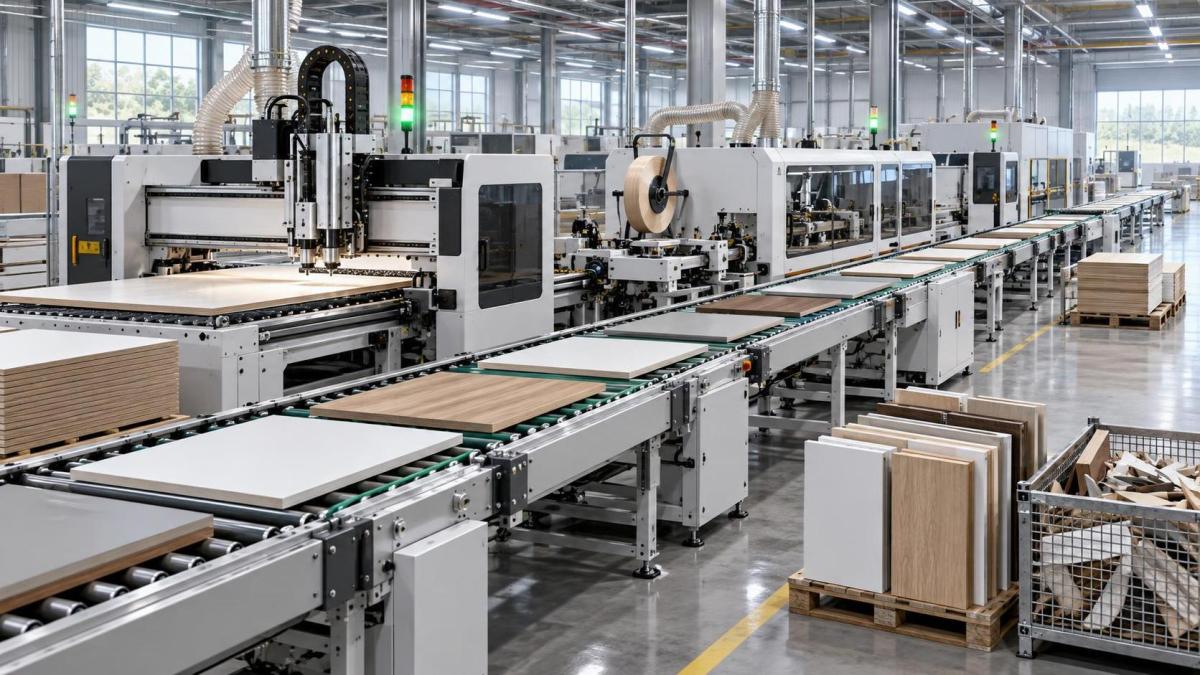
“Automation” is too broad to evaluate as one financial object. A high-speed folder gluer designed to reduce manual handling has a different economic logic from a CNC woodworking cell intended to support one-piece flow. Likewise, an offset press upgrade may be justified by less makeready waste and tighter color repeatability, while a corrugated board line investment may depend on board quality consistency, width utilization, and the ability to schedule smaller order quantities without excessive disruption.
Before calculating returns, define the operating constraint the proposal is supposed to remove. In practice, that constraint is usually one of the following:
- Changeovers consume production hours that could be used for saleable output.
- Labor is concentrated in repetitive handling, feeding, sorting, loading, unloading, or quality checks.
- Short custom orders are declined, delayed, or priced too cautiously because they interrupt longer runs.
- Scrap rises during setup, color adjustment, die registration, nesting changes, or manual rework.
- A downstream process cannot keep up with printing, cutting, drilling, or panel preparation.
- Production planning is unable to see actual machine status, queue time, material use, or job completion in time to act.
A proposal that names several problems without identifying the binding constraint deserves more work. Adding speed upstream does not create financial value when bottlenecks remain at die-cutting, drying, material staging, edge finishing, packing, or dispatch. The first discipline in an approval process is to separate technical capacity from usable capacity.
Build the baseline from production reality, not nameplate capacity
Equipment brochures commonly state maximum sheets per hour, panels per shift, linear meters per minute, or cycle time under favorable conditions. Those figures are useful for engineering comparison, but they should not be used as the baseline for a return calculation. Financial analysis needs the output that can be consistently produced with the actual product mix, substrate range, operator availability, maintenance pattern, setup sequence, and quality requirements of the plant.
Use a representative operating period and capture the current state in enough detail to expose lost time. For each relevant work center, distinguish scheduled hours from productive hours. Then classify the difference: planned setup, unplanned stoppage, material waiting, job approval delay, maintenance, cleaning, quality hold, operator absence, or downstream blockage. The categories should be specific enough to show which losses the proposed investment can plausibly change.
The baseline should also distinguish a temporary problem from a structural one. For example, overtime caused by a seasonal peak does not automatically justify a permanent fixed asset. Conversely, repeated delays on small custom furniture orders may reveal a durable mismatch between the installed production system and the order profile. The relevant evidence is not one difficult month, but a recognizable pattern across demand, scheduling, and cost.
Translate flexibility into cash-flow drivers
Flexibility normally produces value through four channels: cost avoidance, cost reduction, margin capture, and risk reduction. The first three can often be modeled directly. The fourth matters, but it should not be used as a vague residual benefit to make a weak payback appear acceptable.
Cost avoidance is not the same as savings
An automated cell may allow a facility to handle expected order growth without adding a shift, leasing external capacity, hiring scarce skilled operators, or purchasing another conventional machine. This is a legitimate benefit, but it is a cost avoided in a defined future scenario, not a current expense reduction. The model should identify the triggering condition: expected demand volume, required service level, anticipated staffing gap, or outsourced workload. Without that condition, cost avoidance can become an assumption that is difficult to audit.
Cost reduction must reach the income statement
Reduced labor hours are often overstated because an automated line still needs operators, setters, programmers, quality personnel, material handlers, and maintenance technicians. A credible calculation asks what will happen to the released hours. Will overtime decline? Will temporary labor be reduced? Will open positions remain unfilled? Will employees move to another constrained process that generates additional contribution? Or will payroll remain unchanged?
The same distinction applies to waste. Lower setup scrap has an immediate value only when the calculation includes the actual consumed material, inks, adhesives, edge banding, tooling wear, energy, disposal, and rework cost that are avoided. Revenue should not be assigned to scrap reduction unless the saved material allows additional sales that can be fulfilled and invoiced.
Margin capture requires a demand test
Flexible manufacturing can create revenue by making short runs, customized carton formats, versioned printed packaging, variable-size cabinetry, or mixed panel orders commercially viable. That opportunity should be assessed order by order or segment by segment. The relevant question is not “Can the equipment make more variants?” It is “Which currently unserved or constrained orders have positive incremental contribution after materials, labor, logistics, selling cost, and the operational burden of serving them?”
Finance teams should be wary of treating all additional throughput as revenue. If demand is fixed, faster production may reduce lead time without creating more sales. That can still be valuable where service reliability protects retention or reduces penalties, but the value must be described accordingly. Margin growth should be included only where commercial teams can identify demand, pricing, and feasible conversion.
Calculate investment cost as a system, not a machine invoice
The purchase price is usually the most visible number and rarely the complete capital requirement. Flexible automation often changes material flow, utilities, controls, software, tooling, safety arrangements, spare-parts needs, and training requirements. A line can meet its technical specification while underperforming financially because these supporting elements were treated as incidental.
A complete cash outflow estimate should include equipment, freight, installation, commissioning, foundations or floor work where applicable, electrical and compressed-air modifications, extraction or dust-control changes, interfaces with upstream and downstream equipment, software integration, initial tooling, operator and maintenance training, startup consumables, and contingency for defined implementation risks. Working capital also deserves attention. Higher availability may require different raw-material buffers, while shorter lead times may reduce work in progress; either change affects cash.
Do not ignore recurring costs introduced by the new process. These may include service contracts, software subscriptions, replacement wear parts, specialized adhesives, energy consumption, preventive maintenance, programming support, calibration, and cybersecurity or data-management responsibilities for connected systems. A proposal that compares gross annual benefits with only the initial purchase price is incomplete.
Use a layered return model rather than one optimistic ROI number
A single percentage can hide too much. For approval purposes, build the model in layers so reviewers can see which benefits are firm, conditional, or strategic. Start with a conservative base case made up of benefits with a clear operational pathway. Add an expected case only where demand, execution plans, and resource assumptions support it. A downside case should test the consequences of slower ramp-up, lower utilization, incomplete labor realization, or a product mix that does not achieve the projected changeover improvement.
The core calculation can be expressed simply:
Annual incremental operating cash flow = realized labor impact + material and quality savings + avoided external cost + incremental contribution margin − new recurring operating cost − incremental tax effects where applicable.
That cash flow should then be evaluated against total project cash outflow over the expected economic life, using the organization’s required financial measures. Depending on internal practice, that may include payback period, net present value, internal rate of return, or a capital hurdle comparison. No single measure should override the others. Payback helps assess exposure and liquidity; discounted cash flow helps compare benefits and costs occurring at different times; scenario analysis shows how sensitive the conclusion is to execution.
The timing of benefits matters as much as their amount. Installation downtime may reduce near-term output. Operators may need time to achieve repeatable setup performance. Programs, cutting patterns, print profiles, and material recipes may require adjustment. Include a ramp curve rather than assuming full benefit starts on the commissioning date. This is especially important where the investment depends on integrated workflow data rather than a standalone machine replacement.
Test the assumptions that most often break the case
In print, converting, corrugated, and woodworking environments, return models often fail at the interfaces. A new cutter may be faster, but job release data may still be late. An automated edge bander may improve consistency, but panel identification, nesting accuracy, and material staging can still cause waits. A high-speed press may reduce running cost per sheet, but frequent small jobs can make plate, proofing, wash-up, and approval discipline more important than nominal speed.
Pressure-test the proposal with questions that expose those dependencies:
- Which current loss category will decline, and what feature or process change causes that decline?
- Does the expected product mix match the machine’s efficient operating range, including substrates, panel sizes, board grades, and lot sizes?
- Can upstream preparation and downstream finishing absorb the new pace without adding cost elsewhere?
- Are projected labor benefits based on removed payroll, lower overtime, avoided hiring, or redeployed capacity? Who owns that action?
- What percentage of the anticipated incremental orders is supported by identifiable demand rather than general market potential?
- What happens when a critical sensor, tool, print unit, glue system, spindle, or software connection is unavailable?
- Are maintenance capability, spare-parts lead time, and operator skill included in the operating plan?
These questions are not designed to reject automation. They prevent a sound technical improvement from being approved on an unsupported financial premise. In many cases, the analysis reveals that the right investment is smaller or staged: workflow integration before a major line replacement, targeted material handling before full automation, or a pilot cell that validates assumptions around custom-order demand and setup behavior.
Separate operational flexibility from commercial complexity
More variants are not automatically more profitable. Flexible equipment can tempt an organization to accept low-margin, high-disruption orders simply because it has the capability to process them. Approval should therefore include operating rules for the capacity being created. These might define minimum contribution by order type, surcharge logic for difficult substrates or urgent changes, release cutoffs, approved routing rules, and limits on exception work that bypasses normal planning.
This is particularly relevant in customized furniture production, where one-off designs may create unique machining, drilling, edging, and assembly requirements, and in packaging, where version changes can introduce artwork control, color approval, tooling, and material complexity. The financial return depends on using flexibility selectively, not filling newly available machine time with unpriced variability.
Make benefit ownership part of the approval
A capital model becomes more dependable when every major benefit has an operational owner, a measurement method, and a review date. Production may own changeover reduction and yield. Maintenance may own availability targets and preventive-maintenance readiness. Planning may own schedule adherence and queue reduction. Commercial teams may own conversion of identified custom-order opportunities. Finance should validate that reported benefits are incremental and not double-counted across departments.
Post-implementation tracking should compare actual performance with the same baseline definitions used in the request. If setup time falls but total productive output does not improve, the constraint may have moved. If output rises but margin does not, the mix or pricing may need attention. If labor hours fall without payroll impact, the benefit should be reclassified rather than reported as a hard saving. This discipline protects future investment decisions as much as it evaluates the current one.
The strongest approval case does not claim that flexibility has a universal premium. It shows precisely where a flexible manufacturing asset converts lost hours, material loss, labor exposure, constrained demand, or outsourced work into cash flow—and where it does not. That is the standard needed to decide whether an automation investment should proceed now, be phased, or wait until the operational and commercial assumptions are strong enough to support it.
Related News
Get weekly intelligence in your inbox.
No noise. No sponsored content. Pure intelligence.
